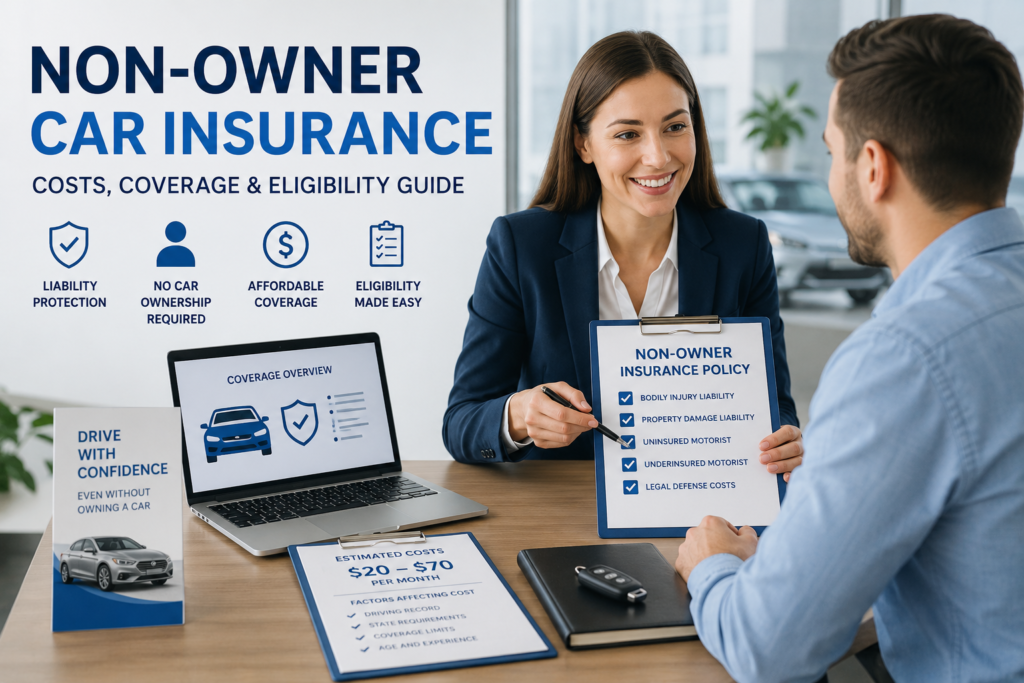
Introduction
Car insurance is often associated with vehicle ownership, but not every driver owns a car. Millions of Americans regularly drive borrowed vehicles, rental cars, or company-owned automobiles without having a vehicle registered in their name. For these individuals, non-owner car insurance can provide an affordable and effective way to maintain liability protection.
As auto insurance regulations continue to evolve in 2026, understanding how non-owner car insurance works has become increasingly important. Whether you frequently rent cars, need an SR-22 filing, or simply want continuous insurance coverage, a non-owner policy may be the ideal solution.
This comprehensive guide explains non-owner car insurance costs, coverage options, eligibility requirements, benefits, limitations, and tips for choosing the best policy.
What Is Non-Owner Car Insurance?
Non-owner car insurance is a liability insurance policy designed for licensed drivers who do not own a vehicle. Unlike traditional auto insurance, which covers a specific car, non-owner insurance covers the individual driver.
The policy primarily provides liability coverage when driving vehicles that belong to someone else. It serves as secondary coverage after the vehicle owner’s insurance policy has been exhausted.
For example, if you borrow a friend’s car and cause an accident, the vehicle owner’s insurance will generally pay first. If damages exceed their policy limits, your non-owner insurance may help cover the remaining liability costs.
This type of insurance is particularly useful for:
- Drivers who frequently borrow vehicles
- Individuals who rent cars often
- Drivers required to maintain SR-22 or FR-44 filings
- People between vehicle ownership periods
- Drivers seeking continuous insurance history
Why Non-Owner Car Insurance Matters in 2026
Auto insurance premiums continue to rise due to increasing repair costs, advanced vehicle technology, inflation, and higher medical expenses resulting from accidents.
According to industry estimates, even a minor accident can result in thousands of dollars in liability claims. Serious accidents involving injuries may generate claims exceeding $100,000.
Non-owner insurance helps protect drivers from financial hardship while ensuring compliance with state financial responsibility laws.
Key benefits include:
- Affordable liability protection
- Continuous insurance coverage
- Lower future insurance premiums
- Legal compliance
- Peace of mind when driving borrowed vehicles
Who Needs Non-Owner Car Insurance?
Frequent Rental Car Users
If you rent vehicles several times per year, purchasing liability coverage from rental companies can become expensive.
A non-owner policy often provides year-round protection at a lower overall cost.
Drivers Without Personal Vehicles
Many city residents rely on:
- Car-sharing programs
- Borrowed vehicles
- Short-term rentals
- Employer-provided transportation
A non-owner policy ensures liability protection whenever they drive.
Drivers Requiring SR-22 Insurance
Certain traffic violations may require drivers to file an SR-22 or FR-44 certificate.
Non-owner insurance often satisfies these legal requirements when the driver does not own a vehicle.
Drivers Between Vehicles
If you’ve recently sold your car but plan to purchase another later, maintaining continuous insurance coverage can help avoid future premium increases.
What Does Non-Owner Car Insurance Cover?
Coverage varies by insurer and state, but most policies include several core protections.
Bodily Injury Liability
This coverage pays for injuries sustained by other people when you are responsible for an accident.
Covered expenses may include:
- Emergency medical treatment
- Hospitalization
- Rehabilitation
- Lost wages
- Legal settlements
Property Damage Liability
Property damage coverage helps pay for damage caused to:
- Other vehicles
- Buildings
- Fences
- Utility poles
- Public property
Uninsured Motorist Coverage
Available in many states, uninsured motorist protection helps cover injuries caused by drivers who have no insurance.
Underinsured Motorist Coverage
This protection applies when the at-fault driver’s insurance limits are insufficient to cover damages.
Legal Defense Costs
Many insurers include legal defense expenses associated with covered liability claims.
What Non-Owner Insurance Does Not Cover
Understanding exclusions is essential before purchasing coverage.
Most non-owner policies exclude:
Collision Coverage
Damage to the vehicle being driven is typically not covered.
Comprehensive Coverage
Protection against:
- Theft
- Fire
- Flooding
- Vandalism
- Falling objects
is generally unavailable under non-owner policies.
Personal Vehicle Coverage
If you own a vehicle, you usually need a standard auto insurance policy instead.
Household Vehicles
Most insurers will not cover vehicles regularly available within your household.
Business Use
Commercial driving activities often require separate insurance.
Eligibility Requirements
Not everyone qualifies for non-owner car insurance.
You Must Not Own a Vehicle
This is the primary qualification.
Individuals who own a registered vehicle typically need traditional auto insurance.
Valid Driver’s License
Applicants must possess a valid driver’s license and meet state licensing requirements.
No Regular Access to Household Vehicles
Insurance companies may deny coverage if you regularly drive a vehicle owned by someone living in your household.
Acceptable Driving Record
Although high-risk drivers may still qualify, severe violations can affect pricing and eligibility.
Average Cost of Non-Owner Car Insurance in 2026
One reason many drivers choose non-owner insurance is affordability.
Average annual premiums include:
| Driver Type | Annual Premium |
|---|---|
| Low-Risk Driver | $250 – $500 |
| Average Driver | $400 – $850 |
| High-Risk Driver | $900 – $2,500+ |
Average monthly premiums:
- Low-risk drivers: $20–$45
- Average drivers: $35–$70
- High-risk drivers: $75–$200+
Compared with traditional auto insurance policies, non-owner coverage is often significantly less expensive.
Factors That Affect Insurance Costs
Driving History
Previous accidents and violations increase premiums.
Age and Experience
Young drivers typically pay higher rates because insurers view them as higher risk.
State Insurance Requirements
States with higher minimum liability limits generally have higher premiums.
Coverage Limits
Higher liability limits provide more protection but increase costs.
Credit-Based Insurance Scores
In many states, insurers may use credit-related factors when determining rates.
Non-Owner Insurance vs. Standard Auto Insurance
| Feature | Non-Owner Insurance | Standard Auto Insurance |
| Covers Specific Vehicle | No | Yes |
| Liability Protection | Yes | Yes |
| Collision Coverage | No | Available |
| Comprehensive Coverage | No | Available |
| SR-22 Eligibility | Yes | Yes |
| Cost | Lower | Higher |
Drivers who own vehicles generally require standard auto insurance, while occasional drivers without cars often benefit from non-owner coverage.
State Regulations and Financial Responsibility Laws
Almost every U.S. state requires drivers to demonstrate financial responsibility.
Common minimum liability requirements include:
- Bodily injury per person
- Bodily injury per accident
- Property damage liability
Several states have strengthened digital insurance verification systems in 2026, allowing law enforcement agencies and motor vehicle departments to instantly verify insurance status.
Drivers should always review their state’s current minimum coverage requirements before purchasing a policy.
Advantages of Non-Owner Car Insurance
Lower Premiums
Because no specific vehicle is insured, premiums are generally much lower than standard auto insurance policies.
Continuous Insurance History
Insurance gaps can lead to higher future premiums.
Maintaining a non-owner policy helps preserve insurance history.
Asset Protection
Liability claims can result in significant financial losses.
Insurance helps protect savings, wages, and other personal assets.
Rental Car Savings
Frequent renters may save money by carrying year-round liability protection rather than purchasing coverage from rental agencies.
Legal Compliance
Many drivers use non-owner insurance to satisfy state insurance requirements.
How to Choose the Best Non-Owner Car Insurance Policy
When comparing insurers, consider the following:
Coverage Limits
Choose limits sufficient to protect your assets.
Customer Service Ratings
Review claim satisfaction and customer support records.
SR-22 Availability
If required, confirm that the insurer offers SR-22 filing services.
State Compliance
Ensure the policy meets all state-specific requirements.
Financial Strength
Select insurers with strong financial ratings and reliable claims-paying ability.
Is Non-Owner Car Insurance Worth It?
For many drivers, the answer is yes.
Consider a scenario where you borrow a friend’s vehicle and cause an accident involving multiple injuries. Liability costs could easily exceed tens of thousands of dollars.
Without insurance, you may be personally responsible for these expenses.
A non-owner policy offers affordable protection and can provide substantial financial security for occasional drivers.
Conclusion
Non-owner car insurance remains one of the most affordable and practical insurance solutions available in 2026. It offers liability protection for drivers who do not own vehicles while helping maintain continuous insurance coverage and comply with state laws.
Whether you frequently rent cars, borrow vehicles from family or friends, require SR-22 filing, or simply want additional financial protection, a non-owner policy can provide valuable peace of mind. Before purchasing coverage, compare multiple providers, understand policy exclusions, and choose liability limits that adequately protect your financial future.
What Changed Since 2024: A Regulatory Timeline
None of these are about you, and all of them show up on your renewal.
| Year | Change | Effect on non-owner buyers |
|---|---|---|
| 2024 | Federal short-term plan rules tightened; auto rate filings accelerate | Indirect: more uninsured drivers, higher UM/UIM value |
| 2025 | California minimum liability rises to 30/60/15 | CA non-owner floors rose; minimum-limit policies cost more |
| 2025 | Several states approve double-digit personal auto rate increases | Renewal increases with no change in record |
| 2026 | Continued repair and medical severity inflation | Property damage and BI lines both repriced upward |
| 2026 | More carriers tighten non-owner underwriting | Manual review, more “access to vehicle” questions |
| 2026 | Telematics expands, but rarely to non-owner products | Fewer usage-based discounts available |
State Minimum Limits in 2026
Minimums are a compliance floor, not a protection level.
| State | Minimum BI/PD | Recent change |
|---|---|---|
| California | 30/60/15 | Raised from 15/30/5 in 2025 |
| Texas | 30/60/25 | Unchanged |
| Florida | 10/20/3 + $10k PIP | PDL-only minimum; FR-44 after DUI |
| New York | 25/50/10 | Unchanged; PIP required |
| Pennsylvania | 15/30/5 | Unchanged |
| Illinois | 25/50/20 | Unchanged |
| Ohio | 25/50/25 | Unchanged |
| Georgia | 25/50/25 | Unchanged |
| Michigan | 20/40/10 + PIP | PIP choice levels now available |
| Arizona | 15/30/10 | Unchanged |
Rate Filings and What They Mean for Your Renewal
Personal auto rates are filed with state regulators. When a filing is approved, the carrier applies it to new business immediately and to renewals at the next term. That produces the pattern every non-owner buyer notices eventually:
- Your first renewal rises 5-15% with no claims and no tickets.
- The increase is larger in states with active litigation environments.
- Shopping at renewal recovers part of it, because a competitor’s filed rate may lag by a quarter.
- Waiting two renewals without shopping usually costs more than any single discount you can earn.
2026 Eligibility Tightening: What Carriers Now Ask
- “Do you have regular access to any vehicle?” – answer literally; a “yes” can end the non-owner quote.
- “Have you had continuous coverage for the past 12 months?” – the database is checked, so the honest answer saves a rewrite later.
- “Is any vehicle registered at your address?” – household vehicles affect eligibility and exclusions.
- “Will you use this policy for rideshare or delivery?” – a “yes” moves you out of the personal product entirely.
- “Provide proof of prior insurance” – a declarations page, not a payment screenshot.
None of these questions are traps; they are the underwriting file. The trap is answering them optimistically and getting a policy that excludes your actual driving.
Frequently Asked Questions
Did non-owner insurance get more expensive in 2026?
In most states yes, driven by rate filings and higher repair and medical severity. Renewal increases of 5-15% with a clean record have been normal for two years.
Did state minimum limits change in 2026?
California raised its minimums to 30/60/15 in 2025 and other states have active proposals. Always verify the current minimum with your state DMV or insurance department before quoting.
Why do carriers ask about vehicle access now?
Non-owner underwriting depends on whether you have regular use of a vehicle. Carriers tightened this question after claims involving undisclosed household vehicles, which are excluded from the policy.
Does a rate filing affect existing policies?
It applies at your next renewal, not mid-term. That is why an unchanged policy can renew at a higher price and why shopping at renewal is the only effective response.
Are non-owner policies still available in 2026?
Yes, though availability varies by carrier and state. Some national carriers have narrowed appetite, which makes independent agents and non-standard carriers more important than they were three years ago.
Should I lock a 12-month term in a rising market?
Usually yes. A 12-month term delays the next re-rate by six months versus a six-month policy, and in a market where filings are still trending up, that is worth 5-10%.